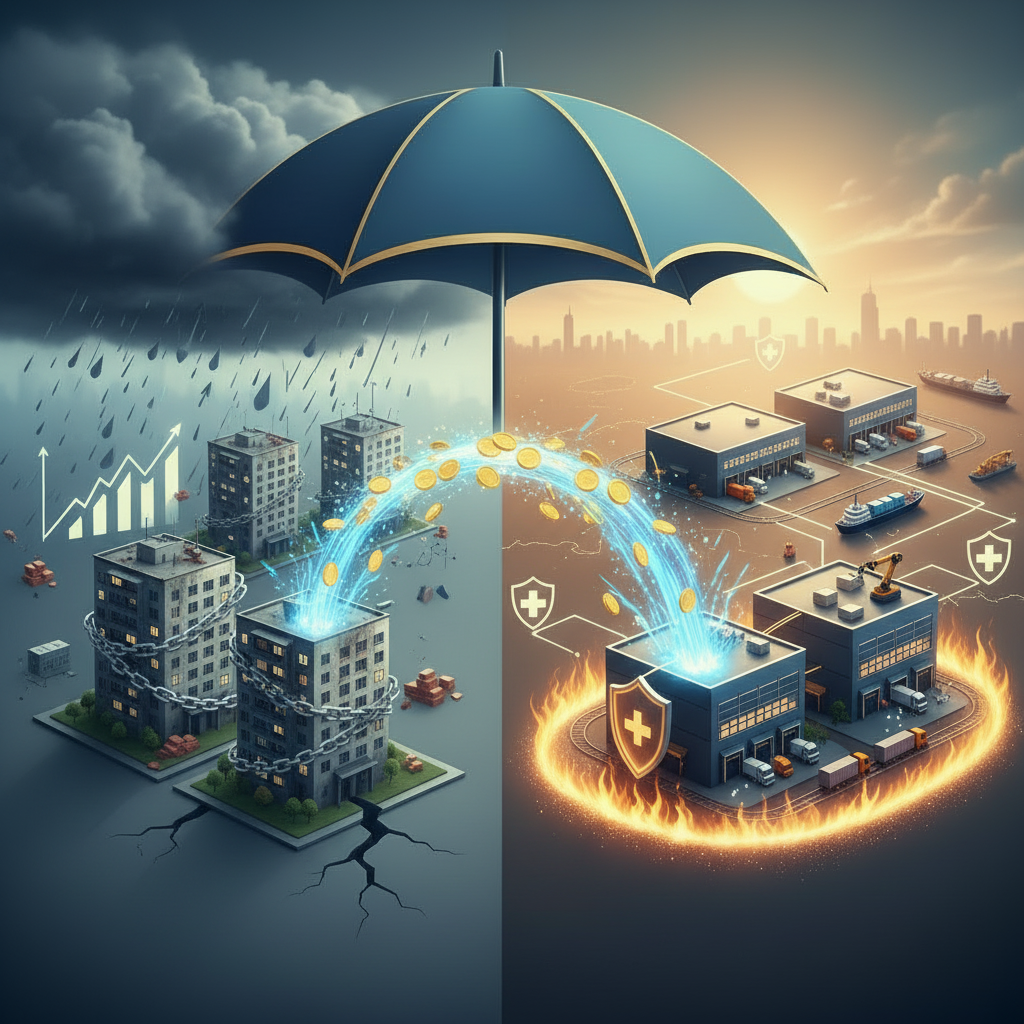
The Capital Shift: Industrial Security Over Housing Headaches
Singapore’s sovereign wealth investor, GIC, is orchestrating one of the most aggressive, silent realignments of institutional real estate capital seen in Europe this cycle. In a sequence of swift tactical maneuvers, the multi-billion-dollar fund is systematically cutting ties with underperforming residential models to build an impenetrable firewall of logistics and industrial supply-chain infrastructure.
The defining stroke of this geographic overhaul is a €2.5 billion capital and portfolio asset transfer into GIC's premier, wholly owned platform, P3 Logistic Parks. Concurrently, GIC has pulled the emergency brake on its sprawling residential joint venture, ordering an immediate tactical review of its €4 billion partnership framework with Amsterdam-headquartered Orange Capital. Taken together, these moves expose a deep structural reality: institutional capital no longer believes traditional residential real estate can outrun macro inflation or the realities of a high-for-longer monetary environment.
The Central Bank Trap: Residential Yields Compressed
For nearly a decade, sovereign wealth funds and ultra-high-net-worth investors treated Western European residential portfolios as safe, bond-like proxies capable of delivering predictable, inflation-linked cash flows. However, the aggressive monetary tightening cycle sustained by global central banks has thoroughly upended that thesis.
Residential property yields have fundamentally failed to outpace current capital costs, pinned down by heavy domestic regulatory intervention, strict rent control laws, and rising maintenance outlays. For an investor of GIC’s scale, the mathematical reality is stark: residential real estate is yielding sub-optimal real returns when weighed against risk-free sovereign debt or corporate credit.
By contrast, the European industrial and logistics sector offers a far cleaner mechanism to capture structural global inflation. Modern supply hubs, big-box distribution centers, and urban e-commerce warehouses operate under long-term corporate leases that feature aggressive, uncapped indexation clauses. When global supply chains experience friction or manufacturing costs surge, logistics landlords pass those expenses directly down to tenants via rising rent indexes. GIC's massive €2.5 billion injection into its P3 platform represents a direct bid to capture these highly resilient corporate margins, effectively treating industrial concrete as a high-yield, inflation-proof alternative to corporate bonds.
Shaking Up the Supply Chain
This macro philosophy is translating into aggressive operational micro-management. GIC’s capital reallocation is not just about writing checks for new developments; it is about ruthlessly optimizing existing infrastructure. This was made clear when the sovereign fund abruptly swapped out its third-party asset managers for its newly acquired £1.2 billion UK and Irish logistics footprint.
The £1.2 billion multi-regional UK portfolio, initially acquired in a blockbuster trade from Blackstone, represents critical, Grade A warehousing concentrated across key logistics bottleneck zones. By changing the operational guard, GIC has signaled to the broader market that macro headwinds leave no room for passive ownership. To combat tightening capitalization rates and rising debt refinancing costs, the fund is demanding immediate, aggressive lease-up strategies and strict cost management from its new operational partners to extract every available basis point of yield.
A Warning Flare for Private Wealth Investors
GIC’s multi-billion-euro real estate rotation should serve as a stark warning flare for private wealth offices, family trusts, and multi-asset pension investors who remain heavily over-indexed to traditional residential property funds. Institutional giants are abandoning the asset class in favor of the strict structural tailwinds of modern manufacturing networks and automated logistics.
While retail residential properties face localized economic stagnation and intensifying regulatory pressure, industrial assets remain protected by severe supply shortages and unyielding corporate demand across prime European distribution corridors. The message out of Singapore is unequivocal: the era of passive residential appreciation is over. Future real estate alpha belongs entirely to those who own the physical infrastructure underpinning the global supply chain.